Impulse spending can derail financial goals and leave individuals feeling regretful about their purchases. Developing a clear budget and setting specific savings goals can significantly curb this behavior. By identifying triggers and implementing strategies to manage spending, anyone can take control of their finances and prioritize saving.
Creating a list before shopping helps people focus on essential items, minimizing distractions. Additionally, using waiting periods before making non-essential purchases gives time to evaluate whether the item is genuinely needed. Awareness of one’s spending habits is crucial, and maintaining a daily or weekly spending log can support this process.
Moreover, finding alternatives to shopping, such as engaging in hobbies or physical activities, can address the emotional aspects of impulse buying. Building a support system with friends or family can also encourage accountability. By applying these strategies, individuals can transform their approach to spending and work towards a more secure financial future.
Understanding Impulse Spending
Impulse spending refers to unplanned purchases that can derail a budget and impact financial health. Recognizing the factors that lead to these buying decisions can help individuals address and mitigate impulse buying behavior.
What Is Impulse Spending?
Impulse spending involves making unplanned purchases without considering their necessity. These purchases often stem from emotional triggers rather than rational decision-making. Common examples include buying a snack while grocery shopping or purchasing clothing during a sale.
This behavior can lead to overspending, as individuals may not account for these transactions within their overall financial planning. Understanding impulse spending is crucial for anyone looking to improve their financial habits and avoid unnecessary debt.
Common Spending Triggers
Several factors can trigger impulse spending, including emotions, environmental cues, and marketing tactics. Emotional triggers such as stress, boredom, or sadness can lead to unplanned purchases as a way to cope or find temporary happiness.
Environmental cues like store displays, online advertisements, or promotional emails can also encourage impulse buying. Additionally, social influences, such as friends or family encouraging purchases, may further contribute to these spending habits. Identifying these triggers can empower individuals to resist the urge to spend.
The Impact of Impulse Buying on Financial Health
Impulse buying can significantly impact financial health. Frequent unplanned purchases accumulate over time, leading to a lack of savings and potential debt. This behavior can disrupt budgeting efforts and make it challenging to meet financial goals.
Moreover, individuals may experience feelings of guilt or regret after impulse purchases, which can create a cycle of emotional spending. By recognizing the consequences of impulse buying, individuals can take steps to develop healthier spending habits and maintain better control over their finances.
Building Strong Financial Habits
Establishing strong financial habits lays the groundwork for effective money management. By focusing on clear goals, tracking expenses, budgeting appropriately, and controlling discretionary spending, individuals can enhance their financial well-being.
Setting Clear Financial Goals
Setting financial goals provides direction and motivation. Goals should be specific, measurable, achievable, relevant, and time-bound (SMART). For instance, saving $5,000 for a vacation within 12 months can focus efforts.
Individuals should differentiate between short-term and long-term goals. Short-term goals might include building an emergency fund, while long-term goals could involve saving for retirement, or owning one of the homes for sale madera ca, for instance. Documenting these goals helps reinforce commitment and keeps progress visible. This can provide a clear roadmap to track progress and stay motivated on the path to achieving financial stability and success.
Many people find that buying a house is their biggest financial milestone. In areas where the cost of living is lower, this goal is often more reachable than expected. For example, new construction homes in Lufkin TX have affordable entry points for first-time buyers. These properties provide a stable environment for families and help them build long-term equity. Having a specific target like this makes it easier to stay disciplined with a monthly budget.
Tracking Expenses and Monthly Spending
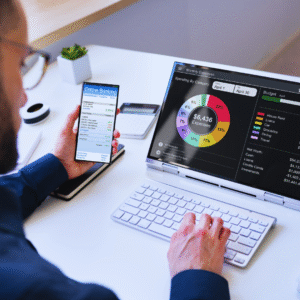
Accurate tracking of monthly expenses is crucial in maintaining awareness of spending habits. Individuals can use spreadsheet applications or budgeting apps to record daily expenditures. Categorizing expenses into necessary and discretionary spending helps identify areas for potential savings.
Reviewing these records monthly can highlight patterns and trigger adjustments in spending. Awareness of where money goes each month promotes accountability and assists in making informed financial decisions.
Budgeting for Success
Creating a budget is an essential step in managing personal finances. A budget outlines income and allocates funds toward necessities, savings goals, and discretionary spending. The 50/30/20 rule can be an effective guideline: 50% of income on needs, 30% on wants, and 20% on savings.
For those planning major financial steps, housing often becomes a key part of the equation. Exploring options within Kansas City MO Real Estate, for example, requires careful budgeting to balance affordability with long-term goals. Factoring in costs like down payments, maintenance, and taxes can help create a more realistic financial plan.
Individuals should regularly review and adjust their budgets. Life circumstances change, and budgets should reflect current financial situations. Using budgeting tools can simplify the process, helping to stay on track with financial intentions.
Controlling Discretionary Spending
Discretionary spending often presents opportunities for impulsive purchases. To manage this, individuals should set specific limits on categories like dining out and entertainment. Creating a spending plan for these categories helps establish boundaries.
Furthermore, awareness of emotional triggers that lead to impulse spending can prompt preemptive measures. Mindfulness techniques, like waiting 24 hours before making a non-essential purchase, can reduce impulsive behavior.
Practical Strategies to Reduce Impulse Purchases
Implementing practical strategies can significantly help in curbing impulse spending. These strategies focus on creating awareness of purchasing habits, preparing for shopping trips, and managing payment methods effectively.
Using the 24-Hour Rule
The 24-hour rule is a powerful strategy to combat impulse purchases. It involves waiting a full day before buying non-essential items. When a person feels the urge to purchase something, they should pause and consider if it is truly needed.
This waiting period allows time to reflect on the decision. Often, individuals find that the desire to buy fades after 24 hours. They may realize the item is not necessary or is simply a response to momentary emotions.
When employing this rule, one might keep a list of items they consider purchasing. After the waiting period, a review can determine if the item is still desired. This practice encourages more deliberate spending habits.
Shopping With a List
Creating a shopping list is an effective way to limit unnecessary purchases. Before heading to a store or shopping online, individuals should list the items they genuinely need. Sticking strictly to this list reduces the chance of deviating toward impulse buys.
It can be helpful to categorize the list by sections, such as groceries or household items. This organization helps maintain focus during shopping trips. If a desired item is not on the list, the individual can choose to revisit the 24-hour rule instead.
Additionally, avoiding shopping while hungry or emotional can minimize distractions. Each time a shopper adds something outside their predetermined list, they should ask themselves if it adds value to their lives.
Limiting Credit Card Usage
Limiting credit card usage is another practical approach to reducing impulse purchases. Credit cards can make it easier to buy on a whim since they allow immediate access to funds without physical cash. Using cash instead can create a more tangible sense of spending, which can lead to better decision-making. Alternatively, setting a specific spending limit on credit cards helps control expenses.
In many cases, individuals may benefit from leaving cards at home when shopping. This reduces the temptation to make spur-of-the-moment purchases. If using a credit card is necessary, taking only one for emergencies ensures better spending discipline. By following these strategies, an individual can cultivate healthier financial habits and reduce impulse spending effectively.
Boosting Savings and Achieving Financial Stability
Establishing effective strategies can lead to increased savings and greater financial security. Focused efforts in automating savings, building an emergency fund, strengthening credit scores, and reducing financial stress contribute significantly to robust financial health.
Automating Savings Contributions
Setting up automatic transfers to a savings account simplifies the savings process. When a specific amount is automatically deducted from a checking account, it reduces the temptation to spend those funds impulsively.
- Choose an Amount: Determine what percentage or fixed amount of your income can be saved regularly.
- Select Frequency: Adjust the transfer schedule—weekly, biweekly, or monthly—based on income flow.
- Utilize High-Interest Accounts: Consider moving savings into accounts that offer higher interest rates, enhancing growth.
Automation enables consistent saving without conscious effort, leading to significant accumulation over time.
Building an Emergency Fund
An emergency fund acts as a financial safety net, providing security during unexpected events. Such a fund should ideally cover three to six months of living expenses.
- Determine Monthly Expenses: Calculate fixed and variable monthly costs to define the target fund size.
- Start Small: Focus on saving a small, manageable amount initially; even $500 is a solid baseline.
- Gradually Increase: Continuously add to the fund until reaching the targeted amount.
Having an emergency fund can prevent reliance on credit during crises, ultimately enhancing financial stability.
Strengthening Your Credit Score
A strong credit score is vital for securing loans and favorable interest rates. It reflects an individual’s ability to manage credit responsibly.
- Pay Bills on Time: Late payments significantly harm credit scores. Setting reminders or automating bill pay reduces this risk.
- Limit New Credit Inquiries: Frequent applications can lower scores. Aim to apply for credit only when necessary.
- Keep Credit Utilization Low: Ideally, use less than 30% of available credit to maintain a healthy score.
Focusing on these practices not only improves scores but also enhances financial options in the long run. Now, this will also support long-term goals such as buying a home or securing better financing options in the future. Along with maintaining good credit, working with professionals like mortgage brokers company Red Deer can help individuals explore suitable lending options and navigate the process more effectively. Taking these steps together builds a stronger financial foundation and improves overall financial confidence.
Reducing Financial Stress
Financial stress can impede the ability to save and make sound decisions. Identifying and addressing sources of stress is crucial for better financial management.
- Create a Budget: A detailed budget helps track income and expenditures, clarifying financial patterns.
- Seek Professional Advice: Financial advisors can provide tailored strategies and solutions to improve financial health.
- Practice Mindfulness: Engaging in stress-reducing activities can promote clearer thinking regarding expenditures and savings.
By tackling financial stress, an individual positions themselves for improved financial decision-making and increased savings potential.